No. 1
9.6out of 10
Betzino
100% up to £150 on first deposit
- Min. deposit
- £10
- Payout
- 1 h
- Games
- 1,000+
18+. New customers only. Operator T&Cs apply.
Unlike UKGC-regulated sites using real-time Faster Payments, non gamstop bank transfer casinos process funds via unregulated cross-border wires without British consumer protection. Sending money to unlicensed operators removes access to official dispute resolution and exposes UK bank accounts to compliance reviews. Players also face currency conversion charges and potential payout blocks when wiring sterling abroad.
 Written by Alexander Roberts | Bonus terms editor | Updated 2 November 2026
100% up to £150 on first deposit
18+. New customers only. Operator T&Cs apply.
100% up to £250 no free spins
18+. New customers only. Operator T&Cs apply.
250% up to £1000 no free spins
18+. New customers only. Operator T&Cs apply.
200% up to £3,000 + 100 FS
18+. New customers only. Operator T&Cs apply.
100% up to £1000 + 100 FS
18+. New customers only. Operator T&Cs apply.
100% up to £100 + 100 FS
18+. New customers only. Operator T&Cs apply.
100% up to £1,000 + 100 FS
18+. New customers only. Operator T&Cs apply.
100% up to £2000 + 150 FS
18+. New customers only. Operator T&Cs apply.
150% up to £750 + 50 FS
18+. New customers only. Operator T&Cs apply.
100% up to £500 no free spins
18+. New customers only. Operator T&Cs apply.
Operating outside British jurisdiction means a non gamstop casino bank transfer is excluded from the domestic Faster Payment System and leaves players without statutory protection. All operators holding a Gambling Commission licence must participate in GamStop as a mandatory condition effective from 31 March 2020. Because unlicensed sites lack domestic banking integration, they cannot use UK sort codes and instead rely on international wire routing.
| Banking Parameter | UKGC-Licensed Casinos | Non-GAMSTOP Offshore Sites | Financial Risk to Player |
|---|---|---|---|
| Payment Network | Faster Payments and Open Banking | International IBAN and SWIFT wires | Loss of domestic payment security |
| Currency & FX Fees | Direct GBP sterling settlement | Foreign currency conversion applied | Deductions on deposits and payouts |
| Settlement Time | Real-time clearing 365 days per year | Multi-day cross-border manual clearing | Delayed access to withdrawn funds |
| Dispute Resolution (ADR) | Free independent ADR after 8 weeks | No UK-recognised dispute scheme | Unrecoverable balances if blocked |
Pay.UK has operated the domestic Faster Payment System since 2008, supporting real-time sterling transfers 365 days per year for individual payments up to one million pounds, whereas a bank transfer casino non uk relies on cross-border clearing. Reviewing our verified list of bank transfer casinos helps identify which payment protections apply under British rules. Comparing domestic banking standards against offshore wire conditions demonstrates why only UK-regulated platforms provide a 365-day real-time settlement network.
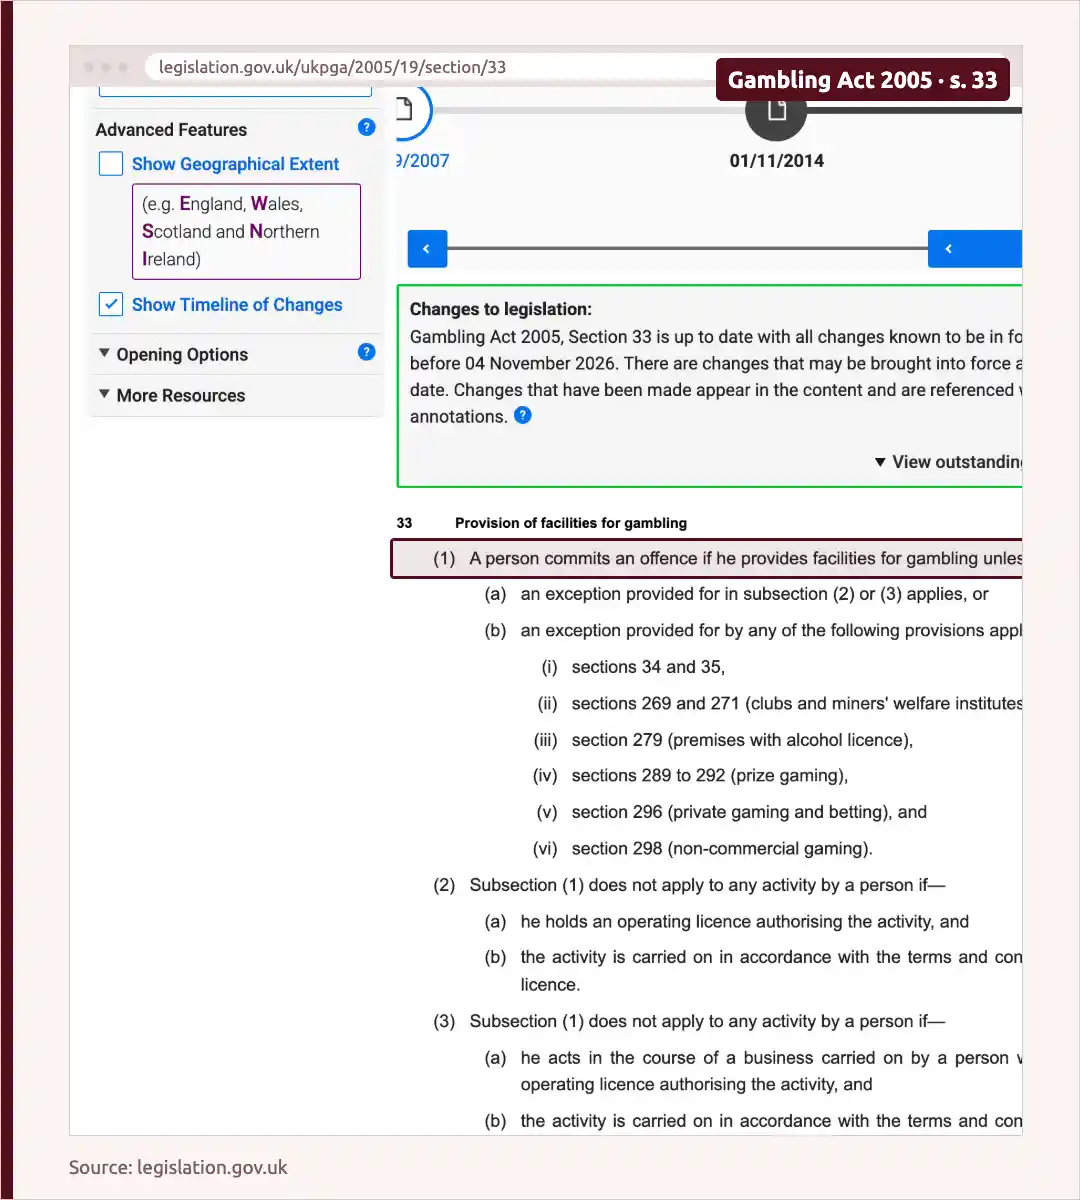
Under Section 33 of the Gambling Act 2005, providing gambling facilities to British consumers without a Gambling Commission operating licence is a criminal offence. This legal prohibition applies regardless of where in the world the operator or its receiving bank account is located. Before initiating any wire transfer, players should check the official register because licensed businesses must clearly display their permit status.
A common mistake is assuming that tax or credit rules change when wiring money abroad. Under British rules, customer gambling winnings incur 0 tax regardless of the amount won, as duty is levied on operators' Gross Gambling Yield, and HMRC confirms betting does not constitute trading. Furthermore, the Gambling Commission prohibits businesses from accepting credit card payments for gambling, so funding any bank transfer via credit facilities violates domestic regulatory standards.
A gambling licence issued in another country does not permit an overseas operator to provide gaming facilities or accept bank transfers from consumers in Great Britain. Unlicensed operators citing overseas certificates still breach Section 33 when targeting British residents, leaving your wired funds completely outside UK consumer protection laws.
Wiring GBP sterling to non gamstop bank transfer casinos triggers double currency conversion and international SWIFT handling charges that reduce your actual balance. Because unlicensed sites lack British sort codes, deposits travel via cross-border networks into foreign currency accounts.
Players searching for foreign wire options—sometimes listed in international banking directories under terms like utländska casino bank transfer—often overlook how bidirectional exchange spreads erode both the initial deposit and any eventual return wire. Whereas Pay.UK confirms that domestic Faster Payments organisations set their own transaction limits for fee-free sterling transfers, cross-border wires pass through multiple chargeable stages.
International bank transfers require intermediary correspondent banks to route funds between your UK current account and the offshore casino's acquiring institution. Each intermediary bank along the SWIFT chain deducts a handling charge directly from the principal sum before the wire settles.
High-street and digital UK banks monitor cross-border transfers and can freeze or close personal current accounts that send wires to unlicensed gambling merchants. Because unregulated payment processors cannot use authorised British gaming codes, an offshore bank account for gambling frequently relies on disguised payment descriptors or shell company names.
When a UK bank's compliance team detects mislabelled international wires linked to illegal gambling facilities, the account holder faces fraud inquiries and sudden banking restrictions. Players must verify that a recipient holds a valid Gambling Commission operating licence before authorising any manual wire or Open Banking payment.
Supplying your IBAN, sort code, and identity documents to unregulated operators exposes you to severe data protection failures, identity theft, and financial fraud. The Gambling Commission warns that illegal gambling sites frequently lack secure payment systems and either block payouts outright or set withdrawal limits so high they become unattainable. If sending bank details to gambling sites is tied to money worries, free support is available from the National Gambling Helpline (run by GamCare) on 0808 8020 133.
When an offshore cashier demands unredacted bank statements prior to releasing a wire, players have no guarantee their sensitive financial data is stored safely. Comparing these vulnerabilities against our guide to the safest bank transfer casinos highlights how statutory UK data and payment audits protect your banking credentials.
Authorising an international bank wire to an unlicensed casino leaves you with zero recourse through British Alternative Dispute Resolution (ADR) providers if your funds disappear. Under Gambling Commission rules, players at licensed sites must first complain directly to the operator and can escalate unresolved disputes to a free, independent ADR provider after 8 weeks.
Even within the regulated sector, an ADR provider will not accept complaints regarding a general customer service issue, focusing strictly on transactional and contractual disputes. Outside the licensed framework, neither an ADR body nor the UK regulator has legal authority to compel an overseas bank to return a disputed casino transfer.
Consumers who encounter an unlicensed website accepting UK bank transfers can use the Gambling Commission's confidential reporting service to submit intelligence on illegal gambling. The regulator specifies that this reporting form is strictly for flagging potentially illegal operations rather than resolving individual player complaints or recovering lost funds.
Providing accurate details—such as the offshore IBAN, beneficiary company name, and payment processor shown at the cashier—helps enforcement teams disrupt unlawful payment channels targeting Great Britain.
A common misconception is assuming that a GamStop restriction expires on its own, as the scheme never automatically removes your self-exclusion when your chosen minimum period ends. Operated by The National Online Self Exclusion Scheme Limited (registered in England and Wales), GamStop blocks individuals from signing up for or using online accounts with gambling companies licensed in Great Britain.
When registering, users must select a minimum exclusion period of 6 months, one year, 5 years, or 5 years with auto-renewal, where a new 5-year period automatically begins when the current one finishes. Even after an exclusion is officially removed, GamStop informs licensed operators of your previous registration during a further 7-year post-self-exclusion period.
To deactivate an expired self-exclusion, you must actively contact the GamStop Contact Centre and complete a mandatory minimum 24-hour cooling-off period before access is restored.
No, a gambling licence issued in another country does not permit an operator to provide gambling facilities to consumers in Great Britain. Under Section 33 of the Gambling Act 2005, operating without a UK Gambling Commission licence is illegal regardless of where the business is based.
Unlicensed casinos are barred from the UK domestic banking network and cannot process real-time Faster Payments via British sort codes. Instead, they must route deposits and withdrawals through cross-border SWIFT wires using international IBAN details.
Unlike domestic Faster Payments that settle in real time 365 days per year, international casino wires require multi-day manual clearing across intermediary banks. Moreover, the Gambling Commission warns that some illegal sites block payouts entirely or set unattainable withdrawal limits.
No, independent Alternative Dispute Resolution (ADR) providers and the Gambling Commission only cover transactions with licensed British operators. If an unlicensed offshore site withholds your bank wire, you have no statutory UK consumer protection or ombudsman recourse.
Users must select a minimum self-exclusion period of 6 months, one year, 5 years, or 5 years with auto-renewal. Removal never happens automatically; once the minimum term expires, you must contact the GamStop Contact Centre and wait through a minimum 24-hour cooling-off period.